Tribunal denies fishy business property relief claim
The First-tier Tribunal (FTT) has disallowed a claim for business property relief (BPR), despite the business in question being a long-established fishery. What went wrong?
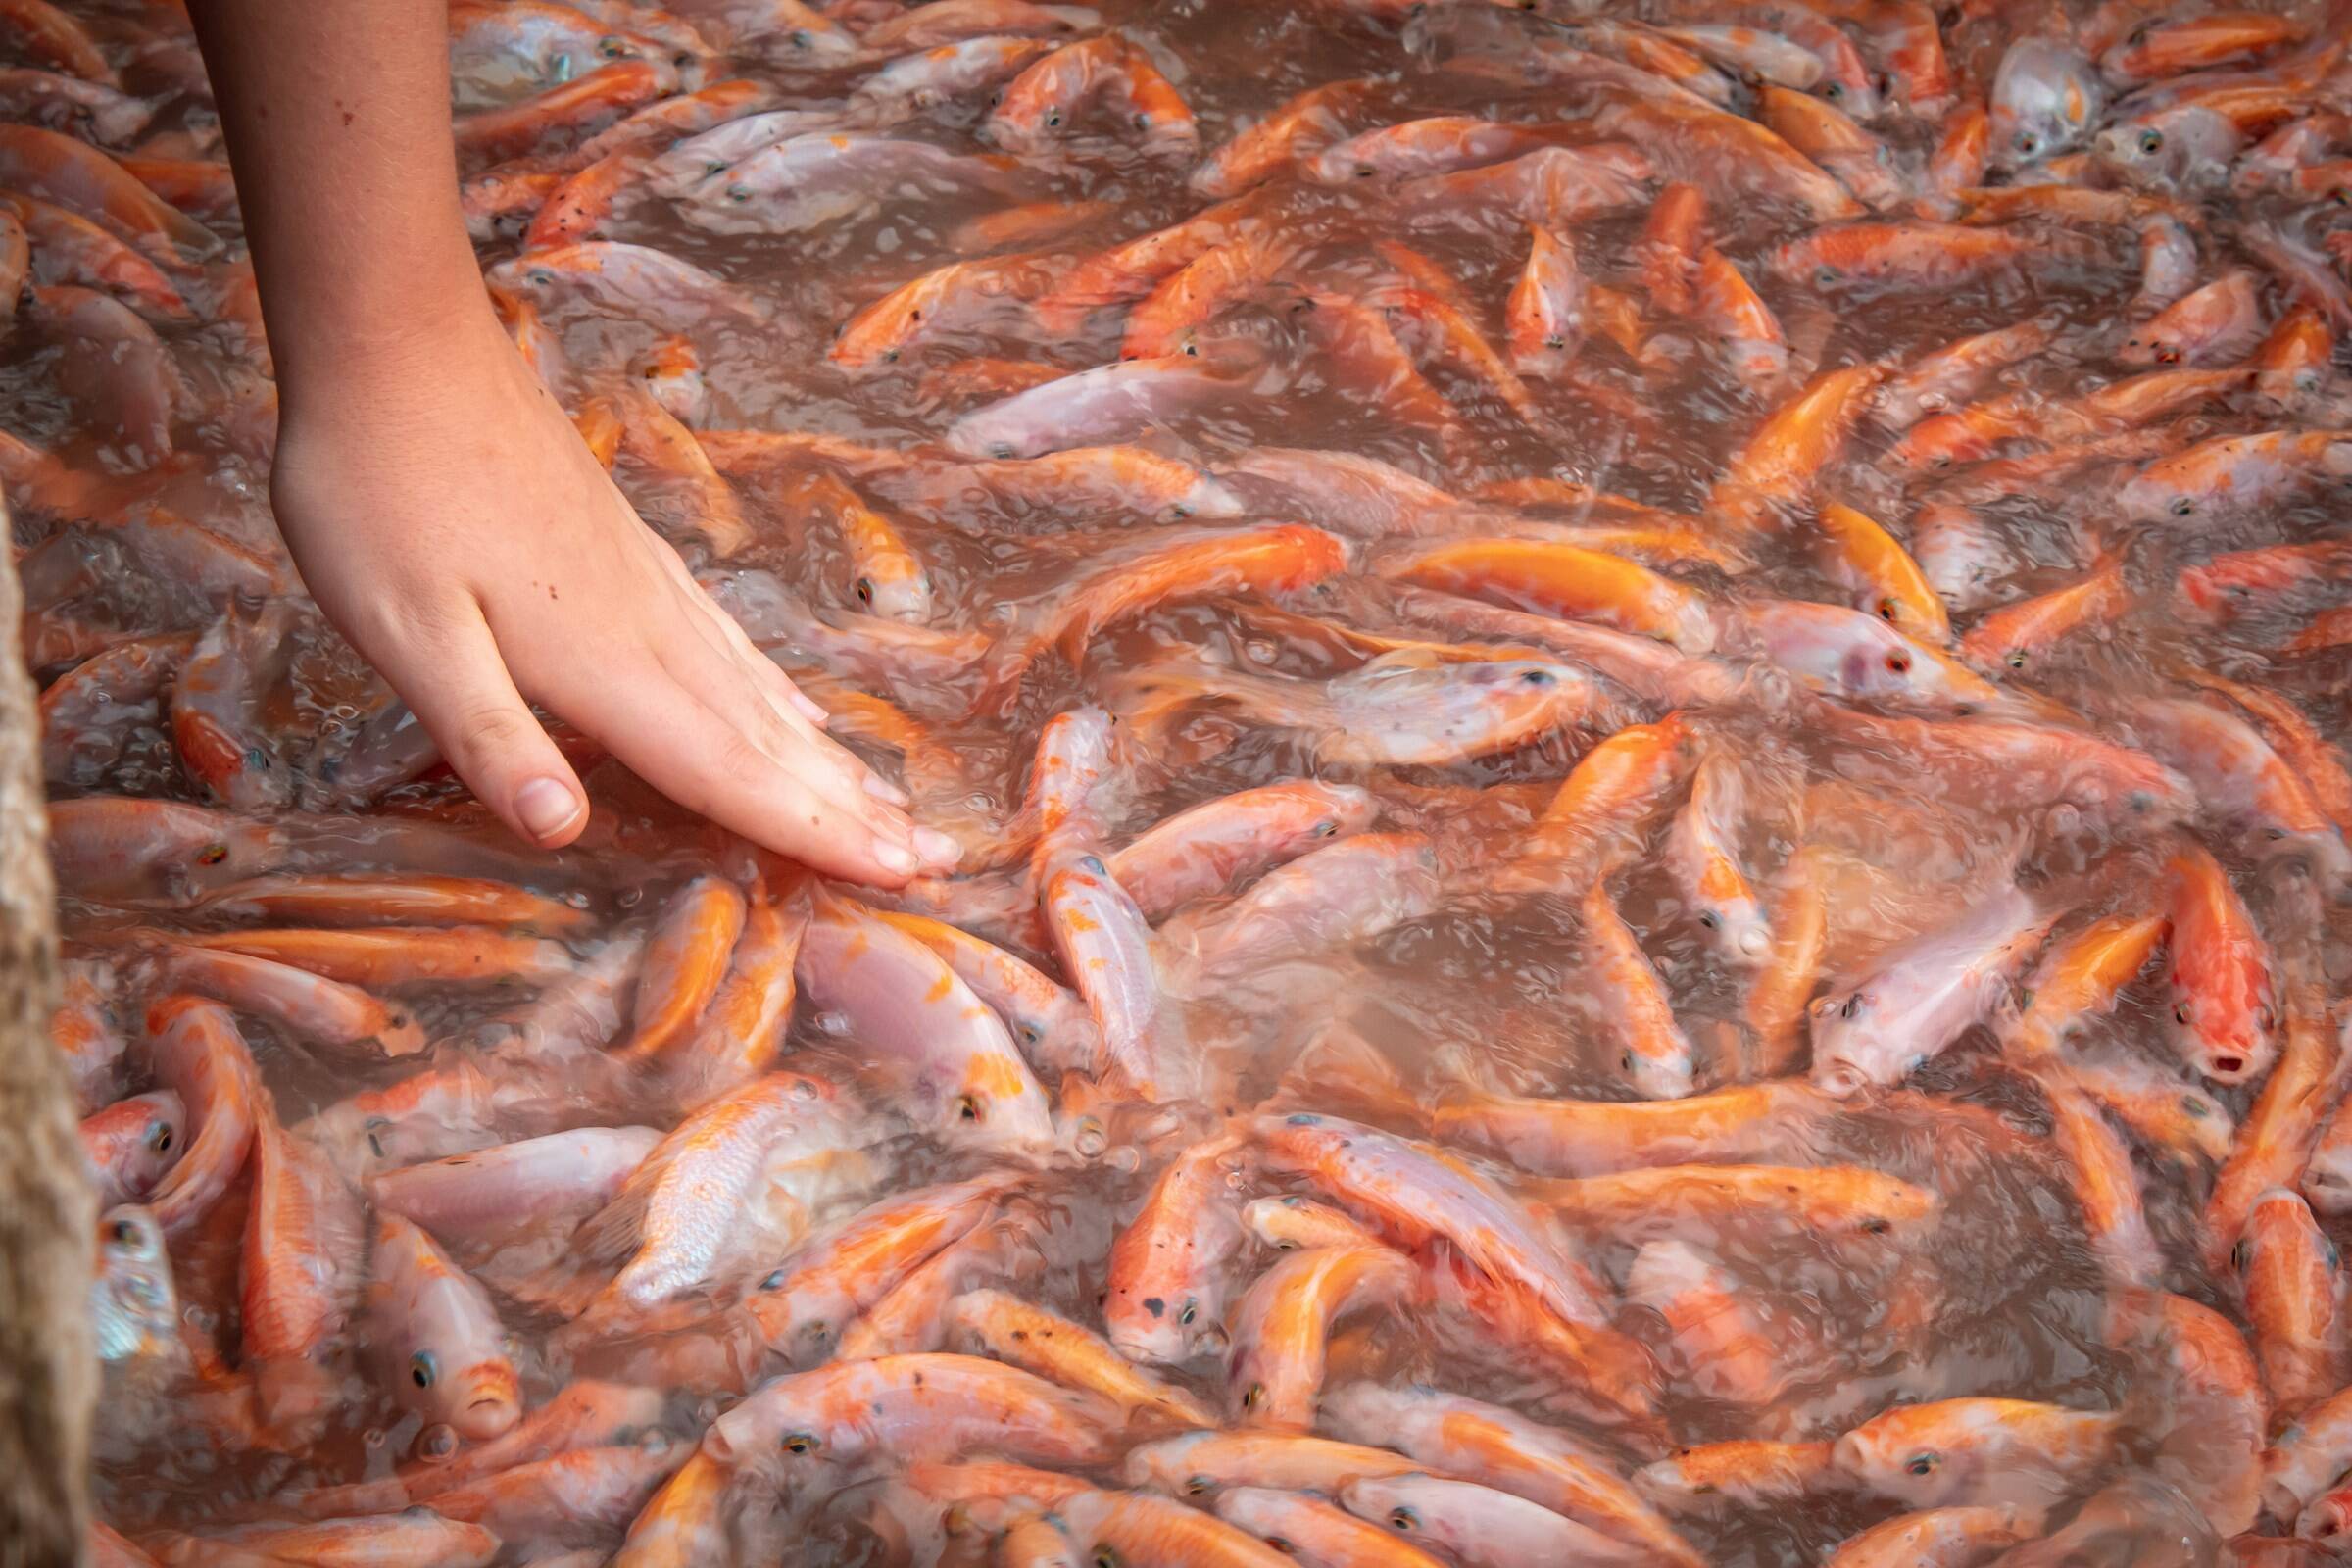
Mrs Pearce (Mrs P) had carried on a fishery business for 17 years, having taken over when her husband died. Mr P had built a profitable stocked fishery business, which involved purchasing fish and stocking his part of the river for members to catch. Each fisherman was allowed to take two fish home. However, shortly after Mrs P took over, the Environment Agency became aware of the impact of stocked fisheries on the native fish and refused to renew fish stocking licences.
The nature of the business therefore changed from being a stocked fishery to the maintaining of a wild fishery. Due to the conservation efforts, members could not use certain hooks and were required to return all fish to the river. The business’ income declined as a result of the changes and made very minimal profits. Members had the use of an outside toilet and car park. Mrs P’s activities included maintaining the land, taking and managing bookings and greeting customers with a drink.
However, the tribunal found that the non-investment activities were not of sufficient significance to tip the balance of the business overall from an investment business to a non-investment business. It was noted that had the business provided services such as tuition in fishing, ghillies to guide the rods, if it had sold or hired equipment or provided catering or a bar the outcome might have been different. In this case, the business had become one of mainly holding land as an investment, by collecting fees from fishermen and maintaining the land. This case highlights the need to regularly review business activities as, despite the taxpayer working very hard in a long established business, the change in responsibilities meant that valuable business relief was not available.
Related Topics
-
Why is HMRC checking PVA more often?
Your business imports goods and accounts for VAT by applying postponed VAT accounting (PVA) on its returns. HMRC is scrutinising returns and issuing large assessments in some cases. What can you do to reduce the risk of getting it wrong?
-
HMRC text or scam? Check before you act
HMRC is contacting some taxpayers by text this week about overdue Self Assessment liabilities and is also sending updates about VAT registration applications. At the same time, it has expanded its guidance on spotting fake HMRC messages on social media. How can you tell whether a message is genuine?
-
Received a P800? Check how HMRC has used your allowances
Some HMRC P800 tax calculations can produce too much tax where a taxpayer has several different types of income and allowances are not allocated in the most favourable way. People with employment or pension income alongside savings, dividends or other income are particularly at risk here. Could HMRC be charging you too much?
 This website uses both its own and third-party cookies to analyze our services and navigation on our website in order to improve its contents (analytical purposes: measure visits and sources of web traffic). The legal basis is the consent of the user, except in the case of basic cookies, which are essential to navigate this website.